(Re)in Summary
- Lenders and investors are driving interest in parametric policies to protect projected revenue, support debt-risk management, and improve a project’s financing profile.
- Asia added 513.3 GW of renewable capacity in 2025, but parametric underwriting appetite varies by peril, location and technology.
- Drought trends, typhoon exposure, severe storms and immature technologies such as floating solar are constraining cover for some projects.
- Insurers are refining triggers using tools such as hail testing, local radar and turbine-specific yield models.
- Hybrid programmes pairing parametric and indemnity cover are expected to broaden appeal among conservative lenders.
- Interest is extending to transmission and distribution networks, battery storage and grid infrastructure.
- Historical patterns point to a shift from El Niño to La Niña in 2027–28, which could raise typhoon and flood risk across the region.
Parametric insurance is gaining traction among Asia’s renewable-energy projects as developers and investors seek protection against weather-driven revenue losses that conventional policies may not cover.
Traditional-market capacity for renewable-energy risks has shrunk over the past two to three years, with gaps persisting even where cover is available, S&P Global reported in June. Projects face “significant non-damage and loss-of-revenue exposures” that conventional products cannot address, said Ben Qin, head of Asia at Descartes.
These include consecutive periods of low wind, solar irradiation or water availability that cut output without damaging equipment. Such volatility worries both equity and debt, Qin said: “[It’s] enough to have an impact on the cost of financing, and sometimes even on the availability of investment.”
Solar irradiation has fallen sharply in Indonesia, Malaysia and Brunei since the start of the century, according to Bloomberg, adding to the weather-related revenue risks renewable-energy projects face.
“Parametric insurance provides a transparent and objective-based solution,” Qin said. “It’s often purchased at the request of lenders and/or investors, who increasingly accept parametric coverage as a guarantee of liquidity.”
By protecting projected revenue and trimming the tail of a project’s revenue-risk profile, cover can lower debt risk, make financing more attractive and “increase project valuations”.
“[It’s] enough to have an impact on the cost of financing, and sometimes even on the availability of investment.”
Ben Qin
Head of Asia at Descartes Underwriting.
Risk-dependent capacity
Asia added 513.3 GW of renewable capacity in 2025, taking its total to 2,891 GW, or 56.1% of global installed capacity, according to Willis. The region accounted for 74.2% of new global capacity that year.
Larger projects, particularly in solar, bring “substantial financing requirements, growing risk exposures and increasing demand for insurance solutions”, said Marcel Andriesse, head of agriculture centre & parametric at Swiss Re, which has completed several larger parametric transactions in the region.
Yet demand does not translate into uniform underwriting appetite. Large drought schemes remain difficult to underwrite, particularly in regions with strong or unpredictable climate trends, Andriesse said. “The insurance industry may be hesitant to cover a persistent trend, but remains willing to provide protection against extreme events. The challenge is to design products that distinguish between these two elements and offer meaningful protection at a sustainable price.”
Technology matters too. Qin said capacity remains “relatively thin” for immature, higher-risk technologies such as floating solar, which Descartes is currently assessing. Because capacity providers take on the risk of an event occurring rather than the size of the loss, they need confidence in the trigger and the science behind it. “Once that’s in place, capacity opens up,” he said.
Location and asset concentration also weigh. Michele Pignoli, head of alternative risk transfer and parametric at Generali Global Corporate & Commercial, said typhoon exposure in the Taiwan Strait, coastal Japan and parts of eastern and southern China constrains cover for offshore wind, where high asset values sit in storm-exposed waters, and repairs can be complex.
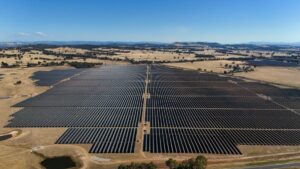
In Australia, hail, severe convective storms and wildfire can push up deductibles or lower sub-limits on conventional cover for utility-scale solar. It’s a gap where parametric cover “can provide an additional layer of protection”, Pignoli said.
Designing triggers around the exposure
Basis risk remains a concern for buyers, though Qin said it was not unique to parametric insurance. With no adjusting process, “the circumstances and amount of a payout are always entirely predictable.”
Andriesse said basis risk had proved “much less of an issue” across Swiss Re’s renewable, agriculture and catastrophe books than industry debate suggested. The harder problem was that “historical experience does not always fully reflect today’s risk environment”, making regular reviews of policy structures increasingly important.
Insurers are nonetheless refining triggers to track actual losses more closely. Descartes has engaged engineers to bombard solar panels with hailstones of various sizes to show how damage varies with intensity, Qin said. The results allow it to structure and price escalating payouts, while localised radar can verify an event and start payment immediately.
For offshore wind, Pignoli said modelling the wind field across a project’s full footprint and at turbine hub height better reflects conditions than checking whether a storm track passes within a fixed radius of a single point. Yield models can also apply the manufacturer’s turbine-specific power curve to link wind speeds with expected production.
Some policies use multiple measures of exposure. Etiqa Malaysia’s Solar Energy Shortfall Insurance, launched in 2023, measures both solar irradiation and energy production, and excludes shortfalls caused by maintenance, equipment breakdown or curtailment.
Hybrid programmes could broaden appeal, according to Pignoli. A parametric component “can provide rapid liquidity following a qualifying event”, while the conventional indemnity programme “subsequently addresses the measured physical damage and longer-term business interruption loss”.
Aon and AboitizPower’s Philippines programme, for example, paired a parametric derivative using regional wind-speed thresholds with a matching named-peril policy issued through a local insurer. Typhoon Rai triggered it in December 2021, and payment was made within 30 days.
“For renewables, product development is likely to extend beyond wind, solar and hydropower production into battery energy storage systems and grid infrastructure.”
Michele Pignoli
Head of ART & Parametric at Generali Global Corporate & Commercial
Grid assets draw growing interest
Qin expects parametric cover to gain ground for transmission and distribution networks, which he described as “typically the most vulnerable but the least-well insured” assets in the sector. Cover can fund recovery, repair and replacement and address interruption and delay, and is already being adopted “on a national or state scale”, he said.
Pignoli identified potential applications including sustained ambient-heat cover for batteries, earthquake triggers for subsea cables and wildfire cover for transmission networks.
“For renewables, product development is likely to extend beyond wind, solar and hydropower production into battery energy storage systems and grid infrastructure,” he said. “These are areas of potential product development, rather than statements that standardised products are already widely available.”
Capacity may also constrain cover for the largest projects, particularly data centres. “The scale of investment in data centres is enormous, and some projects are approaching the limits of what the insurance and reinsurance industry can realistically absorb,” Andriesse said. “Parametric solutions face similar capacity constraints, as ultimately the same risk capital is required.”
“The scale of investment in data centres is enormous, and some projects are approaching the limits of what the insurance and reinsurance industry can realistically absorb.”
Marcel Andriesse
Head of agriculture centre & parametric at Swiss Re
Climate patterns add a further concern. As of September, forecasts indicated El Niño was strengthening and expected to persist through the Northern Hemisphere winter of 2026–27, with historical analogues suggesting a transition to La Niña in 2027–28.
In APAC, La Niña has “historically been associated with increased typhoon activity across the Philippines, Taiwan and South China, alongside heightened flood and cyclone risk in eastern Australia”, said Pignoli. These are regime shifts that reinforce the value of structures that can be recalibrated as hazard data evolves, he noted.
Qin said buyers should use the current window to prepare for a return to hard property-market pricing: “One large storm or earthquake in the wrong place is all it would take.”