(Re)in Summary
- GIFT City is attracting more reinsurance capacity and India-linked business, but underwriting depth remains limited in areas such as cyber, surety and aviation.
- Some of the business moving through GIFT City is migrating from established centres like Singapore and Dubai, rather than representing new business.
- The hub remains a price taker, with underwriting terms and risk appetite still influenced by global markets and cycles.
- Structural barriers continue to limit direct insurance growth, though demand for specialty risks is expected to develop in the near term.
- Expertise and market depth remain to be built at GIFT City to underwrite more complex risks.
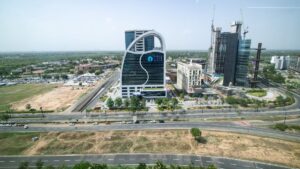
Gujarat International Finance Tec-City (GIFT City) is attracting reinsurance capacity and retaining more India-linked business, but its growing footprint has yet to translate into deeper specialist underwriting, leaving the hub reliant on established global markets for much of its risk appetite and pricing terms.
More reinsurers are establishing operations in GIFT City with an appetite for specialty classes, but relatively few are yet leading or quoting business, said Minesh Jani, CEO of Gallagher Re India. “That is likely to change as more players build local underwriting teams,” he said.
“More reinsurers are establishing operations in GIFT City with an appetite for specialty classes, but relatively few are yet leading or quoting business.”
Minesh Jani
CEO of Gallagher Re India
“Specialty classes like surety, cyber continue to find lead capacity from cross-border reinsurers or foreign reinsurers because appetite within GIFT City remains limited,” said Ankit Mehta, head of broking, P&C at Aon. “Parametric, aviation still continue to be placed with reinsurers outside of India.”
The gap is particularly visible in newer or technically complex classes. Howden Re expects surety and performance bonds, parametric covers, standalone cyber, and life and health reinsurance to become growth drivers, but none is yet at scale, said Ashvita Suvarna, head of facultative reinsurance at Howden India.
“They should be viewed as pipeline rather than confirmed growth lines, although several new entrants have identified them as areas they intend to build,” she added.
Data centres are another emerging area. The scale of planned projects is prompting brokers and reinsurers to deliberate customised solutions, particularly for covers spanning the full data-centre lifecycle.
Marine port package policies, which are still largely placed with cross-border reinsurers, could also become a candidate for GIFT City, Mehta said.
Growth is real, but scale still matters
Gross written premiums (GWP) at GIFT City rose almost tenfold to US$419.16m in the first quarter of India’s FY2027, from US$42.75m a year earlier. That was also more than double the US$202.3m written in the previous quarter.
But the composition of that growth is more telling than the headline number. Reinsurance accounted for US$400.3m of first-quarter GWP, compared with US$186.93m in the previous quarter, while direct insurance contributed US$18.87m, up from US$15.38m.
Suvarna said the increase from about US$102m in 2020 to about US$1.2bn in 2025 shows a strong trajectory, but that percentage growth can overstate GIFT City’s scale relative to established insurance centres.
As of end-June 2026, the International Financial Services Centres Authority (IFSCA) counted eight life insurers, four general insurers, two health insurers and 23 reinsurers in the IFSC. Licensed IFSC Insurance Offices rose to 36 by March 2026, from 24 in December 2025 and 22 in September 2025. Mehta said the regulator is encouraging more players to set up at GIFT City.
However, there is an important caveat to the GIFT City growth story.
“GIFT City is essentially a price taker rather than a price setter, at least at this stage. It is therefore plugged into global market cycles and trends rather than setting its own terms.”
Ashvita Suvarna
Head of facultative reinsurance at Howden India
“GIFT City is essentially a price taker rather than a price setter, at least at this stage. It is therefore plugged into global market cycles and trends rather than setting its own terms,” Suvarna said, adding that conditions remain tied to markets such as London, Singapore and the Middle East.
Nymphea Batra, CEO of Marsh Re India, adds that GIFT City’s advantage is less about a uniform pricing benefit and more about choice, capacity and access to specialist markets. “Pricing will continue to reflect the underlying risk, its complexity, loss experience and the structure of the programme,” she said.
“Pricing will continue to reflect the underlying risk, its complexity, loss experience and the structure of the programme.”
Nymphea Batra
CEO of Marsh Re India
That leaves GIFT City exposed to global underwriting cycles even as its local book expands.
Trade credit, one of its stronger lines, continues to benefit from ample capacity, although underwriters are becoming more cautious amid economic volatility, geopolitical tensions and sector stress. Casualty and liability remain more disciplined globally, and Howden Re expects that discipline to carry through to cessions placed via GIFT City.
Direct insurance expansion hurdles
Reinsurance has grown strongly in GIFT City because insurers there cannot write onshore Indian risks directly.
Gallagher Re’s Jani explained that a primary carrier in GIFT City can write direct business only for clients based in the hub, in India’s other special economic zones, or outside India.
Suvarna said this makes a direct licence relevant mainly to offshore and IFSC-domiciled risks, such as aircraft and ship lessors, IFSC banks and funds, and Indian corporates’ non-admitted offshore exposures. Mainland business stays with insurers admitted by the Insurance Regulatory and Development Authority of India.
Reinsurers in GIFT City do not face that limit. They can accept business from Indian cedents, subject to the regulator’s order of preference. Large or complex onshore risks that need facultative support can therefore still reach GIFT City: an admitted insurer writes the policy onshore and cedes the risk to a reinsurer in the hub.
Batra said direct writing needs distribution, servicing and claims capabilities, and these take longer to build than a reinsurance branch that can draw on existing treaty relationships.
“I think this comes down to infrastructure rather than appetite,” says Suvarna.
Mehta, however, said appetite is a contributing factor, because insurers already have plenty of growth to chase at home. “Insurers already have large onshore opportunity and many are deliberating to establish operations at GIFT City, with plans of looking at opportunities outside of India,” he said.
Marsh Re expects direct business to develop first in large commercial and specialty risks, where the economics suit GIFT City, although direct specialty underwriting remains nascent for now.
“Insurers already have large onshore opportunity and many are deliberating to establish operations at GIFT City, with plans of looking at opportunities outside of India.”
Ankit Mehta
Head of broking, P&C at Aon
Not a challenger to the throne
Much of the business now flowing through GIFT City is not new but has moved from other hubs.
“All lines of products which were otherwise written by the companies in their respective territories are now moving to GIFT City via their branches,” Suvarna said. She expects migration from Singapore and Dubai to continue as Indian cedents and brokers become more comfortable with GIFT City paper.
Mehta said GIFT City reinsurers now support much of the property and casualty business that Indian cedents once ceded to Singapore or Dubai, including premium from reinsurers that previously wrote Indian business on a cross-border basis.
Market experts see GIFT City, along with established centres, serving distinct needs.
“The global insurance market is interconnected, and different centres will continue to serve different purposes,” said Marsh Re’s Batra. The more immediate opportunity is to retain and originate a greater share of India-linked risks in India, particularly large infrastructure, energy, marine, aviation and corporate risks, she added.
Howden’s Suvarna notes, however, that GIFT City still has less global recognition than Singapore and Dubai, so cedents and brokers can default to the familiar hubs rather than actively choose GIFT City.
Building a broader regional role could help change that. India has proposed hosting a BRICS Risk Lab at GIFT City, with member states agreeing to continue discussions on the proposal alongside efforts to explore a voluntary platform for developing common risk models and specialist insurance capabilities across the bloc.
India’s growth prospects and regulatory changes are further strengthening the case. The increase in the foreign direct investment limit for insurance to 100% has removed a longstanding ownership constraint. Suvarna also pointed to projected economic growth of 6.6% in 2026 and Swiss Re’s forecast of average annual premium growth of around 6.9% between 2026 and 2030.
The real test is depth, not entity count
Talent and servicing depth could prove to be the true test of mettle. Licences can be obtained relatively quickly under IFSCA’s unified framework, but developing underwriting expertise and claims capability takes considerably longer.
“The growth suggested by registration numbers may outpace the development of the operational and technical capabilities needed to support a mature insurance market,” Suvarna says.
Malay Poddar, CEO of EarthRe Insurance IFSC Limited, said GIFT City is developing genuine on-the-ground underwriting capability for Indian and Global South risks, but gaps remain in specialised underwriting frameworks, secondary-market and capital-markets links for risk transfer, talent, data infrastructure and operational interoperability.
“Commercial significance will be measured by the quality and resilience of the book rather than simply by volume,” Poddar says.
“Commercial significance will be measured by the quality and resilience of the book rather than simply by volume.”
Malay Poddar
CEO of EarthRe Insurance IFSC Limited
Batra similarly sees the number of entities as a secondary measure of success. More experienced underwriting and claims capability, a stronger broking ecosystem, product innovation and alternative capital, including insurance-linked securities, will matter more.
“The platform has been established,” Batra said. “The next chapter is about building the expertise, capital and market depth needed to make that platform truly consequential.”