Key findings
Finding 01
Medical inflation is structural
Rising treatment costs are only part of the story. Ageing populations, chronic disease, higher utilisation, new medical technologies and changing consumer expectations are creating sustained upward pressure on healthcare costs across APAC.
Finding 02
There is no single APAC market
Healthcare systems, regulation, public-sector involvement, insurance penetration and provider markets vary widely across the region. Insurers need a deep understanding of local market dynamics rather than relying on approaches that work elsewhere.
Finding 03
Product design is central to affordability
Higher deductibles, co-payments, co-insurance, tighter benefit management and more targeted coverage can balance affordability with access to care, while making policyholders more aware of what care costs.
Finding 04
Pricing and risk management must get sharper
Across-the-board premium increases are unlikely to be a sustainable answer. More granular underwriting, closer monitoring of claims trends and greater differentiation between risks can help insurers keep pace with medical costs.
Finding 05
The answer lies beyond the policy
Insurers cannot tackle rising costs through products alone. The industry needs to focus more closely on how care is delivered, with stronger provider relationships and more effective care pathways.
Finding 06
AI is an enabler, not a silver bullet
The technology has uses across underwriting, claims, fraud detection and customer engagement, but it cannot by itself resolve the deeper challenges facing healthcare systems.
Rebuilding APAC’s healthcare insurance model
Special Report
Rebuilding APAC’s healthcare insurance model
As healthcare affordability reaches a crisis point, markets are exploring more sustainable ecosystems.
Before the report
Forewords & Key Findings
This whitepaper was researched and written by (Re)in Asia with an editorial-first approach. It is free to read without a subscription through our commercial partnership with Marsh Re.
About this whitepaper
This whitepaper was researched and written by (Re)in Asia with an editorial-first approach.
It is free to read without a subscription through our commercial partnership with Marsh Re.
In this report
Six findings at a glance
Editor’s foreword
Towards a sustainable model
As healthcare costs continue to rise across Asia Pacific, insurers, providers and governments are facing growing pressure to maintain access to quality care while keeping coverage affordable and sustainable.
The challenge is complex. Medical inflation is being driven not only by the rising cost of treatments, but also by ageing populations, increasing prevalence of chronic disease, and greater utilisation of healthcare systems. At the same time, insurers across APAC find themselves having to navigate significant differences in healthcare systems and the regulations that govern them.
There is no single solution. Rather, the sustainability of healthcare insurance depends on a combination of smarter product design, more sophisticated underwriting and more efficient use of healthcare resources. Technology, including artificial intelligence, also has an important role to play.
This whitepaper explores how insurers and other stakeholders across APAC are responding to these challenges, and what a more sustainable healthcare insurance ecosystem could look like.
With many thanks to everyone who contributed their time and insight to this report.
Blake Evans-PritchardEditor(Re)in Asia
Sponsor’s foreword
Finding common ground
Healthcare and its access are such a hot topic. Against the backdrop of an ageing population, advancements in medicine, and growing care expectations, the cost of healthcare has risen rapidly in recent years. This topic is yet again brought to the fore.
As a stakeholder to the ecosystem, insurers are under the spotlight. Insurers play an important role. They offer products that allow risk pooling, with coverage designed to incentivise good habits and judicious utilisation. These are crucial to keeping care cost affordable. Our success here is unfortunately varied, with many struggling to tame the rapidly rising claim cost.
The challenge to insurers is more than that. Complaints are abundant. From insured lives about insurers being overly stringent on claims, and from medical providers accusing insurers of denying cover for rightful care.
The search for the ever-elusive panacea continues. Marsh Re is working to find common grounds between the stakeholders, an equilibrium that meets their core needs. This whitepaper offers the platform for dialogue. As a stakeholder in the insurance space, Marsh Re is proud to sponsor this platform.
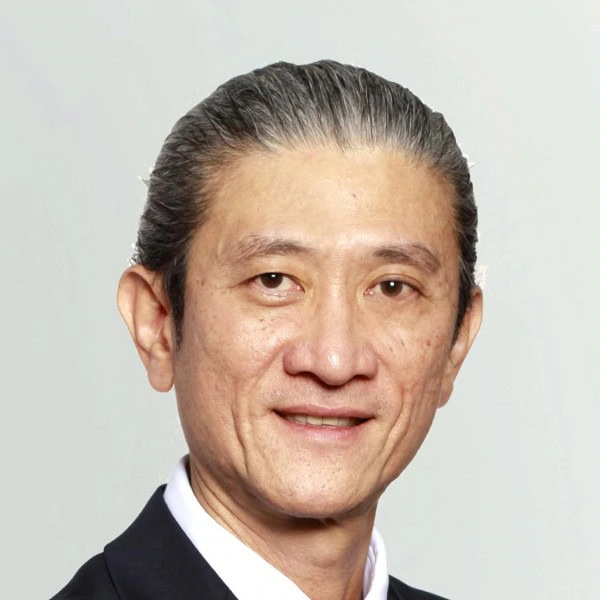
Poh Chee KokSenior Vice President of Health Asia PacificMarsh Re
A defining challenge
01
The rising cost of care
In this chapter
Healthcare systems across Asia are facing a defining challenge: how to maintain access to quality care as medical costs rise, populations age, and traditional models come under increasing pressure.
While there is no single solution to the affordability challenge, insurers, providers, and regulators are experimenting with new approaches – from smarter product design and prevention-led care to a more efficient use of technology.
The challenges facing APAC’s healthcare systems have multiple dimensions.
The cost of individual treatments is rising steeply, but so too is the underlying demand for care, driven by ageing populations, the growing prevalence of chronic disease and greater health awareness. People are consuming more care per person, with earlier diagnosis, more frequent monitoring and greater use of specialist treatments becoming increasingly common.
This is putting pressure on affordability, claims costs and the sustainability of existing insurance models.
The scale of the challenge is reflected in the latest medical inflation figures.
According to data from WTW, APAC is facing a particularly acute medical inflation challenge, with costs projected to rise by 14% during 2026. By contrast, medical inflation in Europe and the United States is starting to level off, although it remains high.
General consumer price inflation is far lower, with the International Monetary Fund projecting it will reach 3.7% this year, even once oil shocks from the Iran crisis are taken into account.
“Medical inflation is not just cyclical – it’s structural and multi-factor,” says Catherine Love Soper, Head of Health Southeast Asia at Munich Re. “Ageing, chronic disease and expensive new treatments are pushing the baseline higher, but just as important (if not more important) are behavioural drivers like overconsumption and overtreatment.”
“Just as important are behavioural drivers like overconsumption and overtreatment.”
Add to that weak pricing transparency and billing discipline, and you get persistent cost escalation, she adds.
“That combination is why inflation has proven so stubborn across cycles,” Soper says.
Medical inflation was exacerbated by Covid-19, with utilisation falling sharply during the pandemic, only to rebound later, resulting in a delayed but sustained surge in claims. This was reinforced by broader macroeconomic shocks, including the Ukraine conflict, which exposed supply chain dependencies and contributed to more persistent input-cost inflation. Inflationary pressure from the oil spike linked to the US-Iran conflict has also not helped.
“Taken together, these factors have made medical inflation structurally ‘stickier’,” says Poh Chee Kok, Senior Vice President of Health Asia Pacific at Marsh Re. “Looking at its underlying components, it is difficult to see this changing. The drivers of medical inflation are, in large part, here to stay.”
“The drivers of medical inflation are, in large part, here to stay.”
These underlying components are common across many countries. Population ageing is increasing the underlying need for care, while advances in medicine are expanding the range of treatments available – often at a higher cost. At the same time, rising affluence and greater access to health information are changing what consumers expect from healthcare, encouraging greater use of services and treatments.
Several APAC markets have already taken steps to try to ease the cost burden.
In Singapore, new cost-sharing rules for Integrated Shield Plan (IP) riders could cut premiums by about 30% on average, according to the Ministry of Health.
Thailand has introduced compulsory co-payment rules in efforts to rein in spiralling costs.
Malaysia has just launched a pilot insurance scheme for more affordable healthcare protection.
In Hong Kong, several insurers have introduced cross-border healthcare protections, allowing local residents to seek medical coverage in China.
While regulatory responses differ across markets, they share a common objective: improving affordability without compromising access to quality care.
Yet despite these efforts, industry participants broadly agree that there is no single measure capable of reversing the structural forces driving medical inflation.
Instead, addressing the challenge will require a combination of reforms, innovation and sustained collaboration across the healthcare ecosystem.
One region, many realities
02
No single APAC market
In this chapter
Long-term medical inflation is an unavoidable feature of just about every country in APAC. However, the precise challenges facing the sector vary—sometimes quite significantly—between markets.
“Every stakeholder in the healthcare ecosystem—providers, regulators, insurers, and professional bodies—is operating within the constraints of their respective systems and mandates. As a result, approaches differ significantly across markets, reflecting varying policy frameworks and regulatory philosophies,” says Poh.
At the most simplistic level, APAC can be bifurcated into two segments: the mature and developed markets (which include Hong Kong, Singapore, Japan and Australia) and the earlier-stage markets (which include much of Southeast Asia). Even here, though, there can be significant variations in the factors driving healthcare cost increases across individual markets.
These differences in market maturity are also reflected in the region’s significant healthcare protection gap.
“We have a wide range of medical products in Asia, from the more traditional primary medical cover to the newer products like medical stop loss for captives,” says Idie Si, Head of Accident and Health, Asia for Berkshire Hathaway Specialty Insurance (BHSI). “With this variety, insurers in markets like Hong Kong and Singapore need to keep an eye on cost containment if they are to make any profit there, while countries like Vietnam and Indonesia are seeing fast growth but are certainly less mature when it comes to product and provider variety.”
Following the Covid-19 pandemic, Hong Kong’s accident and health market experienced a period of profitability pressure, with figures from the Insurance Authority indicating that the sector has only recently returned to positive underwriting results.
According to Si, this return to profitability last year was largely driven by price hikes. While strong market demand allowed many policyholders to absorb the higher costs, the repricing exercise also resulted in the loss of some accounts.
For diversified insurers, profitability from other product lines (such as personal accident and life cover) provides greater flexibility when repricing medical portfolios. Conversely, specialist monoline insurers, such as Bupa, have faced particular challenges in restoring profitability to their Hong Kong books.
Such profitability conversations are playing out across the region, with insurers keen to remain competitive on pricing but anxious not to eat too much into the bottom line. Within higher-growth markets, the reasoning shifts slightly, with many insurers considering a short-term profit hit in pursuit of longer-term growth opportunities. This makes a deep understanding of local market dynamics critical.
“For us, the most important factor when entering the medical market is developing a deep understanding of the local healthcare system,” says Si. “You can look at historical data to set what appears to be the right premium, but they only tell part of the story. Insurers also need to appreciate the nuances of how the local healthcare ecosystem operates—including claims behaviours, provider dynamics and potential fraud risks—or they are exposed to significant challenges. Having a deep understanding of the local market is therefore critical.”
“For us, the most important factor when entering the medical market is developing a deep understanding of the local healthcare system.”
Another key differentiator across APAC markets is the balance between private and public healthcare provision, with the role of government funding and the maturity of private healthcare systems varying significantly from one market to another.
The extent of government involvement is another factor shaping medical cost trends across APAC. In markets with significant public-sector participation, governments can exert greater control over healthcare pricing and reimbursement, helping to moderate the pace of medical cost increases. Where private healthcare plays a larger role, rising demand can leave insurers exposed to provider pricing, utilisation and claims inflation.
Japan provides a clear example of how this dynamic can play out. While it is undoubtedly a mature insurance market, a significant proportion of medical costs—potentially as much as 80%, according to Si—are effectively supported through the public healthcare system. This reflects Japan’s universal public health insurance model, under which the government has a central role in healthcare financing and in setting the framework for medical costs, rather than directly subsidising private medical insurers. Patients typically contribute through out-of-pocket payments, with the remainder funded through insurance premiums and government support.
A system under strain
03
Demand is changing as fast as cost
In this chapter
Medical inflation captures only part of the pressure facing healthcare systems across APAC. Ageing populations and rising rates of chronic disease are increasing demand for care, while changing consumer expectations, broader access and comprehensive insurance coverage can encourage more frequent or intensive treatment.
Andrew Teo, Country Lead for Accident and Health at QBE Singapore, says these pressures are increasingly being felt simultaneously. He cites three core drivers: rising utilisation, increasing costs of care, and demographic change.
Start with utilisation. Teo argues that when insurance coverage is highly comprehensive, there is less sensitivity to the cost of care and a greater propensity to seek treatment – something that Singapore’s Ministry of Health (MoH) refers to as “buffet syndrome”.
Arjan Toor, Chief Executive Officer, Health at Prudential plc, argues that having “skin in the game” creates more awareness around the actual cost of care.
“If everything is covered, why would customers worry about the medical bill?” he says. “I think that having some kind of co-pay or deductible is a positive thing. This creates greater awareness of the overall medical bill and goes some way towards addressing the potential issue of over-utilisation. But it is a careful balance: the amount should not be so high that it discourages people from seeking the care they need.”
It was concerns around over-utilisation that led Singapore to introduce restrictions last year on riders that previously covered deductibles and co-payments. Singapore’s government hopes that they will improve the sustainability of the system, but the restrictions also mean policyholders face greater out-of-pocket expenses.
Insurance design, though, is only one factor driving higher utilisation. Ageing populations and the growing prevalence of chronic disease mean more people require ongoing care. At the same time, people are taking a more active role in managing their health, with expectations around convenience and access also rising.
A recent Bain & Company survey of 6,300 consumers across nine APAC markets found that 84% expected healthcare to be more convenient than it was two years ago, while 71% expected doctors to be more responsive through channels such as phone, WhatsApp or email.
Cost of care is just as significant. Teo says that rising private and specialist costs are hugely difficult for insurers to manage, because healthcare is not a normal commodity.
“People usually do not ‘shop around’ during a medical episode, and the doctor-patient relationship carries a lot of trust and urgency,” he says. “Consequently, manpower, facilities, drugs, implants, diagnostics and advanced treatments become more costly.”
“People usually do not ‘shop around’ during a medical episode.”
Approved medical panels can help with this, steering policyholders towards cost-effective care options and creating a stronger negotiating position with hospitals and specialists. This has become particularly popular in Singapore, offering insurers a way to engage more actively with providers on pricing and claims management.
Demographics add another layer of pressure. As APAC’s populations age, a growing share of people are reaching that stage in life when reliance on healthcare typically increases. This is driving greater demand for chronic disease management, cancer treatment, cardiovascular conditions, orthopaedic procedures and longer care episodes. It is also putting pressure on the supply of care, with widespread staff shortages across healthcare systems. With demand rising faster than capacity, the resulting strain could lead to longer waiting times, tighter availability of care and, ultimately, further upward pressure on costs.
Addressing this challenge requires insurers to adapt their products and risk management strategies to a changing population profile. Greater emphasis on preventive health, early intervention and chronic disease management needs to be matched by more sophisticated underwriting and pricing approaches that reflect evolving claims patterns.
Beyond these three core drivers, several additional factors can amplify claims pressures. These include things such as fraudulent claims behaviour and supply-side constraints – factors that are often viewed as secondary considerations because they do not act in isolation.
Ageing also raises a separate question: how will people fund healthcare later in life? Employer-sponsored health insurance remains an important source of private coverage across many APAC markets, but that protection can disappear when people retire – just as healthcare needs and premiums are increasing. For insurers, this creates a difficult balance between maintaining affordable coverage for older customers and pricing for the significantly higher claims costs associated with age.
Rising to the challenge
04
Move from blunt repricing to precise intervention
In this chapter
The consensus among market participants is that there is no miraculous solution to the challenge of rising healthcare costs waiting around the corner. If there were, it would likely already have been discovered. Instead, navigating the complexities of healthcare coverage is about managing these pressures effectively rather than eliminating them altogether.
Poh argues that the primary mechanism available to the market lies in product design and benefit management.
“This includes not only reductions in annual limits but also tighter controls on access to care, increased requirements for referrals and high levels of co-payments, co-insurance and deductibles,” he says.
Steps are already being taken in this direction in some of APAC’s more mature markets, such as Singapore and Hong Kong, with product design increasingly used to balance affordability with market demand and competitive positioning.
“In practice, this means high deductibles and co-insurance becoming standard to realign incentives and keep costs affordable,” says Sarah Salvilla, Group Chief Health Officer at FWD Group.
“In practice, this means high deductibles and co-insurance becoming standard to realign incentives and keep costs affordable.”
John Zhu, Swiss Re’s Chief Economist for Asia Pacific, adds that such product tweaks are particularly important “in markets where premium adjustments are constrained by regulation or consumer affordability”.
As BHSI’s Si notes, insurers were able to restore Hong Kong’s market to profitability largely through premium increases. However, it remains unclear how much further scope there is for repricing. This suggests that future gains may need to come from product innovation and more sustainable benefit design.
BHSI has recently introduced a medical stop loss product, specifically to help with the rising costs of health insurance that employers in Hong Kong and Singapore are now facing.
The product tailors excess-of-loss cover for individual employees, so that certain low-risk but high-cost treatments (such as gene therapy) are excluded. On top of this, employers can purchase aggregate stop loss cover, which sits across the entire portfolio and guards against unexpected incidents that might affect the entire workforce.
While demand for this product has so far fallen short of expectations, continued pressure on premiums could see interest rise.
Another factor that has become increasingly important for insurers is the quality of their underwriting practices.
“We can no longer rely on across-the-board premium increases alone,” says Teo. “That may protect the portfolio in the short term, but it can also penalise the better-performing segments of the business and healthier risk pools.”
By applying a more granular approach, QBE is able to actively review claims by demographics, industry segment, benefit type, claim frequency and severity.
“That is where underwriting is becoming more proactive,” says Teo. “We conduct portfolio reviews more frequently than before, and pricing is being adjusted based on actual experience and emerging claims trends, rather than relying only on historical averages.”
Outpatient claims, specialist claims, diagnostics, hospitalisation and chronic disease patterns can all behave very differently. At headline level, a portfolio may look acceptable, but once broken down, the pressure may be concentrated in specific sub-segments.
“The underwriting intention is not to simply charge more but to provide more accurate pricing,” says Teo. “If we price too lightly, the portfolio becomes unsustainable. But if we apply blunt increases across the board, we lose good risks, which creates its own anti-selection problem.”
“The underwriting intention is not to simply charge more but to provide more accurate pricing.”
Enter technology
05
Build the healthcare ecosystem, not just the policy
In this chapter
As with all areas of the world these days, there is a great deal of chatter about the benefit that artificial intelligence can bring to healthcare insurance, especially when it comes to lowering prices and making it more sustainable.
“Demand is out of control, supply is constrained, and people are increasingly looking to AI as some kind of silver bullet – but things are more nuanced than this,” says Alex Boulton, Head of Healthcare and Life Sciences Practice for Southeast Asia at Bain & Company.
“Demand is out of control, supply is constrained, and people are increasingly looking to AI as some kind of silver bullet – but things are more nuanced than this.”
One area where AI could have a meaningful impact is in helping to redesign care pathways. Inefficiencies often arise when patients do not enter the healthcare system at the most appropriate point, with some seeking specialist care or hospital-based treatment when primary care or lower-cost settings may be more suitable.
“AI-powered tools could help guide patients towards the right level of care, support clinicians with earlier diagnosis and treatment decisions, and improve coordination across different parts of the healthcare system,” says Boulton.
Other strong cases for AI, as noted by Swiss Re’s Zhu, include underwriting, claims processing and advanced document processing. Swiss Re has developed a cloud-native life and health underwriting suite called MagnumXP, in which underwriting is fully automated for between 80% and 90% of applicants. All of this helps reduce underwriting costs, though Zhu cautions that human judgement is still needed for the most complex cases.
“AI augments human expertise rather than replacing it,” he says.
“AI augments human expertise rather than replacing it.”
AI is also increasingly being used to stamp out fraud, waste, abuse and inefficiency, which Prudential’s Toor says is proving a massive drag on the health insurance industry.
“The difficulty has always been balancing the need to assess claims thoroughly with the customer expectation of a fast and seamless claims experience. AI is becoming an important tool to improve claims efficiency while keeping human judgement at the heart of the process,” says Toor.
By analysing large volumes of claims data, identifying patterns and flagging outliers, AI allows insurers to focus their attention on the claims that may require further investigation, while ensuring legitimate claims can be processed more quickly.
“As a health insurer, we are committed to paying claims. The goal is not to pay fewer claims. It is to make sure we are paying the right claims,” he says.
“The goal is not to pay fewer claims. It is to make sure we are paying the right claims.”
But, as Boulton notes, AI is not a panacea. While it can help insurers and providers manage demand more efficiently, it cannot address the underlying shortage of healthcare capacity or remove the structural factors driving demand higher.
“Ultimately, the opportunity is to take care that is currently being delivered in an expensive setting and move it somewhere more appropriate. AI can help with that, but it is only part of the solution,” says Boulton.
While AI may not eliminate the structural pressures driving healthcare costs, it will become an increasingly important tool in helping insurers build a more efficient, transparent and sustainable health insurance ecosystem.
“I expect AI to have a meaningful impact across multiple dimensions of the insurance value chain. This includes product design—such as pricing and underwriting—as well as operational processes and customer interfaces,” says Poh.
The next chapter
Insurers across APAC have to work out not just how to absorb rising medical costs, but how to help reshape the systems in which healthcare is delivered. With the pressures on the health system unlikely to abate, the industry cannot rely solely on periodic repricing to maintain sustainability.
“Overall, the industry is still in a phase of iterative improvement rather than arriving at a definitive solution,” says Poh. “Progress is being made through incremental adjustments and refinements rather than structural resolution. Each participant in the system is acting in line with its own incentives and obligations, and outcomes reflect the balance of these often-competing priorities. In that context, the evolution of healthcare markets is best understood as a continuous process of adjustment rather than a problem with a single endpoint.”
“The evolution of healthcare markets is best understood as a continuous process of adjustment rather than a problem with a single endpoint.”
In other words, the future of health insurance in APAC is unlikely to be defined by one breakthrough solution, but by a combination of measures that improve sustainability across the healthcare ecosystem. Smarter product design can encourage more appropriate use of care, while stronger provider partnerships and more sophisticated underwriting can help insurers manage costs.
Technology will be an important enabler of these changes. While AI will not remove the structural pressures driving healthcare costs, it can help insurers build more efficient systems by improving decision-making, streamlining processes, supporting better care navigation, and enhancing the customer experience.
Ultimately, the insurers that succeed will be those that move beyond simply paying for healthcare and become active participants in improving how it is delivered. In a region as diverse as APAC, the path forward will not be uniform, but the direction of travel is clear: towards a more collaborative, data-driven and sustainable model of healthcare insurance.