The country's three major non-life groups remain well capitalised after FYE26 earnings were supported by divestment proceeds and better pricing in domestic motor and property lines.
Underlying earnings improved even as equity‑sale gains faded, with strong international profitability and lower nat‑cat losses more than offsetting a softer Japan P&C result.
The parties have six months to conclude negotiations and market analysts believe a deal appears more credible than RHB Bank’s earlier, unsuccessful attempt in 2019.
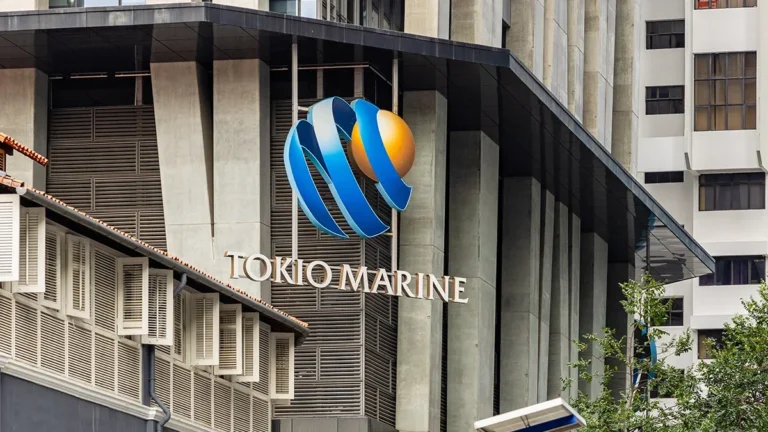
S&P said it expects Tokio Marine to continue expanding internationally through acquisitions and organic growth, while also increasing the share of investment assets held outside Japan.