(Re)in Summary
- Andrew Hare, Marsh Re’s incoming Japan CEO, sees facultative growth in semiconductor and data-centre risks that may not fit existing treaty appetite.
- Japan’s economic value-based solvency regime is widening reinsurance talks to cover capital, earnings volatility and risk appetite, while asset-intensive reinsurance (AIR) deals continue on the life side.
- Justin Ward, Marsh Re’s new Pacific CEO, sees opportunities in cyber, parametric solutions and data-led underwriting, alongside growing interest in insurance-linked securities (ILS) and alternative capital.
- Climate losses outpacing pricing and affordability pressures are the main risks in Australia and New Zealand (ANZ), as regulators reshape expectations on capital, disclosure and claims.
Marsh Re is looking to expand facultative opportunities linked to semiconductor and data-centre risks in Japan, while alternative capital and specialty lines are emerging as priorities in the Pacific, according to the broker’s newly named regional heads.
Speaking to (Re)in Asia about their first-year priorities, Andrew Hare, who will succeed Jeremy Fox as CEO of Marsh Re in Japan on 1 January 2027, said one key focus is deepening the team’s technical and analytical expertise.
Meanwhile, Justin Ward, the newly appointed CEO of Marsh Re Pacific, plans to broaden the broker’s offering from treaty and facultative placements through to capital advisory, structured solutions, ILS and MGA support.
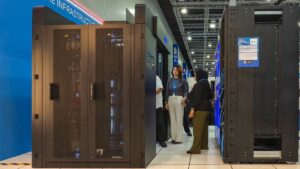
In Japan’s non-life sector, Hare sees the clearest growth opportunities in facultative reinsurance. “Investment in semiconductors and data centres is creating large, concentrated and technically complex exposures that may not fit neatly within existing treaty appetite,” he said.
Tokyo exemplifies this tension well. The city is one of APAC’s most important data-centre hubs, but is also one of the most hazard-exposed locations in the world, facing earthquakes, typhoons and flooding.
Japan and other markets in the region are exploring new grid-access rules that require data-centre operators to take greater responsibility for power resilience, bringing on-site power systems into the scope of what insurers need to assess. The potential for large business interruption losses adds another layer of opportunity, complexity, and risk for reinsurers.
“Investment in semiconductors and data centres is creating large, concentrated and technically complex exposures that may not fit neatly within existing treaty appetite.”
Andrew Hare
Japan CEO, Marsh Re
Beyond specific risks, Hare said the reinsurance conversation in Japan is broadening. “The traditional questions about limit, attachment and price remain fundamental, but they increasingly sit alongside questions about capital, earnings volatility and risk appetite.”
“Japan’s economic value-based solvency framework gives insurers another lens through which to assess those choices,” Hare said. The regime, which took effect on 31 March, aligns insurers’ capital requirements more closely with market risks and asset-liability management.
“That should encourage a more integrated discussion about treaty structure, facultative capacity, retentions and counterparty diversification,” he added.
On the life side, asset-intensive reinsurance (AIR) deals, which free up capital for cedents, increased in the run-up to the new regime and have continued since Japan’s Financial Services Agency tightened its AIR rules in July.
Hare said there is further scope for portfolio solutions and selected life reinsurance, particularly for in-force business, but warned against overstating the opportunity. “Each insurer will take its own view of economics, governance, counterparty strength, collateral and recapture risk.”
“Japan’s economic value-based solvency framework gives insurers another lens through which to assess those choices.”
Andrew Hare
Japan CEO, Marsh Re
Climate, capital and regulation reshape ANZ
Speaking on his new role in the Pacific, Ward identified specialty lines such as cyber and parametric solutions as growth markets.
“The other major opportunity is using better data, analytics and AI to sharpen underwriting, improve claims outcomes and support more tailored products,” he said.
But he puts those alongside ongoing, regionally important perils like flood, hail and fire. “The main risks are that climate losses continue to outpace pricing, while affordability pressures could reduce demand and make some parts of the market harder to sustain.”
Ward also sees an important shift in how the market is being funded. “There’s also a lot of innovation happening in how capital is sourced and structured, with strong global interest in insurance-linked securities, private credit and alternative capital.”
Australian regulation is adapting to that shift. From 1 January 2027, reforms finalised by the Australian Prudential Regulation Authority (APRA) will make it easier for insurers to use catastrophe bonds and other alternative risk transfer.
“There’s also a lot of innovation happening in how capital is sourced and structured, with strong global interest in insurance-linked securities, private credit and alternative capital.”
Justin Ward
Pacific CEO, Marsh Re
Regulators are shaping behaviour in other ways too, Ward said, through expectations around resilience, disclosure and fair dealing in product design and claims.
These include APRA’s planned review of operational and technology risk at general insurers and the Australian Securities and Investments Commission’s 2026-27 priorities for general insurers, which focus on claims handling and premium disclosure. In New Zealand, the Contracts of Insurance Act, which takes effect on 15 November 2027, will end consumers’ duty to volunteer information, require clear policy wording and require insurers to pay claims within a reasonable time.
“The market is responding by becoming more focused on innovation, capital efficiency and transparency, while also seeking to better meet consumer and business needs in a more constrained environment,” Ward said. “That combination is likely to drive more competition, more product development and greater use of alternative capital structures.”
“The market is responding by becoming more focused on innovation, capital efficiency and transparency, while also seeking to better meet consumer and business needs in a more constrained environment.”
Justin Ward
Pacific CEO, Marsh Re